
Las Vegas Joins Miami And Other US Hubs In 9% Tourism Revenue Drop As Sharp Decline In Overseas Arrivals Squeezes Local Economies
-
Travel, Health, Food, Entertainment, Currency
-
-
6 mins
-
Travel and Tour World
-
Srishty Mishra
-


In August 2026, U.S. tourism suffered heavily due to the fall in the number of foreign arrivals leading to a 9% drop in domestic expenditures.
In August 2026, U.S. tourism suffered heavily due to the fall in the number of foreign arrivals leading to a 9% drop in domestic expenditures. In August 2026, the United States’ inbound tourism industry witnessed a drastic contraction, suggesting structural challenges ahead for tourism and hospitality companies dependent on foreign visitors. International visitors’ expenditure declined by almost 5% on a yearly basis to reach $19.9 billion as per the data released by the United States’ National Travel and Tourism Office (NTTO). While the drop in top-line is worth billions of dollars in terms of lost exports, the localized figure shows a far more serious situation. The greatest drop was seen in domestic expenditure which includes hotels, food service, transportation, leisure, and retail and was down by 9% to $10.8 billion. The drastic drop in domestic expenditure can be attributed to the 11.8% fall in overseas arrivals, as mentioned by the U.S. Travel Association.
The Anatomy of the 9% Local Squeeze
To understand the economic devastation of a 9% drop in local spending, one must look at the unique consumption habits of the international tourist. Unlike domestic weekend travelers who might limit dining out or drive their own vehicles, long-haul international visitors represent a captive, high-yield economic demographic. They traditionally stay longer, rely entirely on paid local transportation, eat three meals a day at local establishments, and allocate substantial budgets for luxury shopping and high-ticket entertainment.
When this specific revenue stream contracts to $10.8 billion, the pain is immediately transferred to the municipal level. An 11.8% drop in overall overseas arrivals confirms that this is not merely a case of budget-conscious tourists spending less; it is a fundamental loss of volume. Without this international influx, the massive infrastructure of the American hospitality sector—built to accommodate pre-pandemic growth trajectories—is suddenly oversupplied and under-monetized.
City-by-City Crisis: Where the Economic Bleeding is Heaviest
The national contraction is not distributed evenly. It is disproportionately impacting gateway cities, theme park capitals, and legacy resort towns that have historically over-indexed on foreign arrivals.
Las Vegas: The Desert Oasis Runs Dry
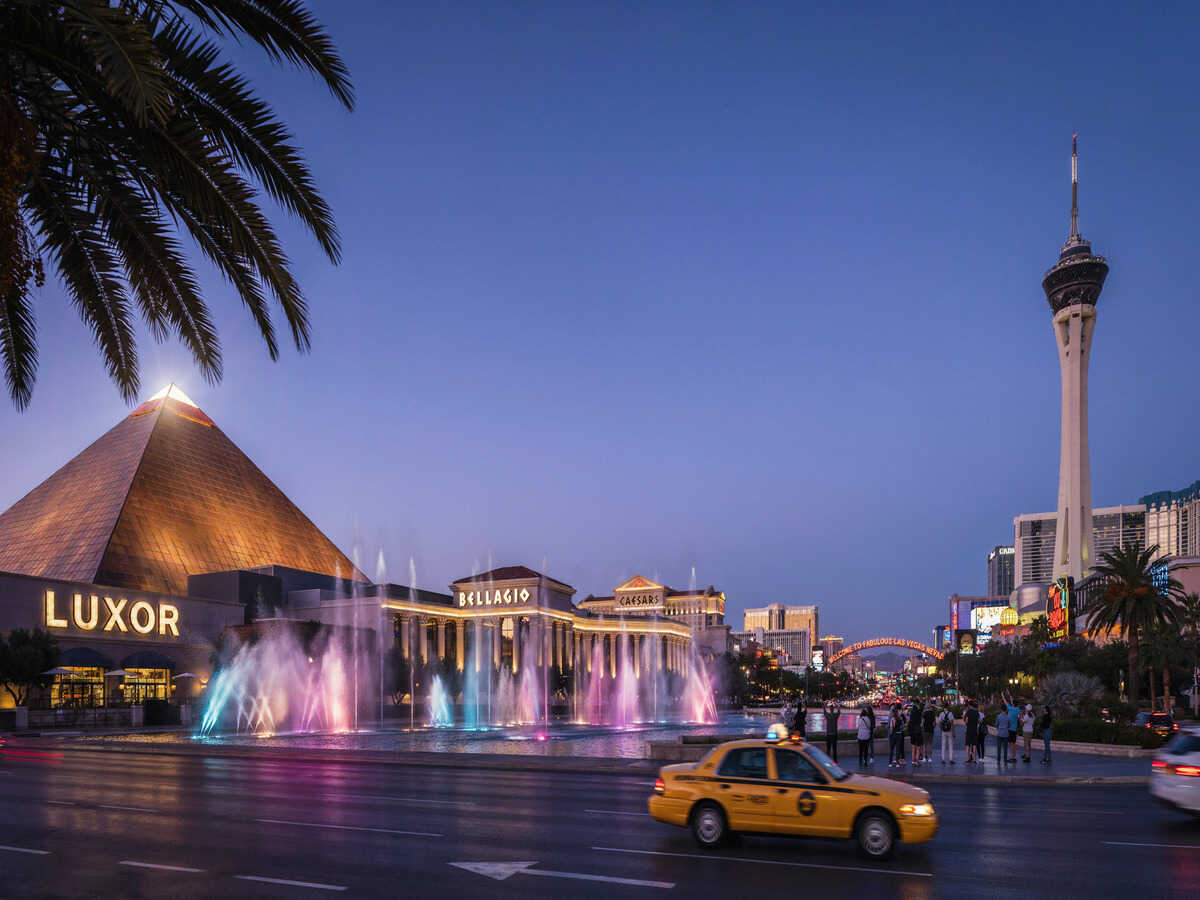
Las Vegas stands at the epicenter of this economic shift, severely victimized by the sudden erosion of its crucial northern feeder market. Canada has historically supplied a steady stream of high-volume tourism to the Nevada desert, but economic pressures and shifting aviation strategies have choked this pipeline. In the first quarter of 2026 alone, Canadian airlines slashed an estimated 82,000 seats destined for Las Vegas. Consequently, overall visitor counts have dropped to levels not witnessed since the recessionary period of 2010 (excluding the anomalous pandemic years). The Las Vegas economic engine requires high-volume crowds to fuel its casinos, retail malls, and entertainment residencies; without them, the local economy faces severe structural pressure.
Miami and the Gateway Cities: The Short-Term Rental Crash
Gateway cities heavily leveraged in the alternative accommodation market are facing a separate crisis. International guests are the cornerstone of the short-term rental economy, generally booking further in advance and staying for extended periods. With August 2026 data showing a 2.3% drop in short-term rental (STR) demand nationwide, municipalities categorized as having “Very High” exposure to international losses—specifically Miami, Florida, and New York City—are bearing the brunt. Cities with “High” exposure, including Los Angeles, San Francisco, and Honolulu, are watching local hosts and property managers face sudden cash-flow shortages.
Orlando: The Family Vacation Priced Out
In Central Florida, Orlando is feeling the sting of global macroeconomic dynamics. As a premier destination for international families, the region is highly exposed to the strength of the U.S. dollar, which has transformed an already expensive theme-park vacation into an unaffordable luxury for many middle-class foreign families. This reality has materialized in municipal ledgers, with Orlando reporting double-digit year-over-year percentage drops in local hotel tax revenues.
The Northern Border States: The Drive-Market Drought
The crisis extends beyond major international airports to land borders and seaports. States relying on vehicular cross-border traffic from Canada, such as Washington State and upstate New York, have felt a localized squeeze. Washington State has witnessed a sharp drop in regional leisure travel, contributing to direct operational cuts. Regional maritime operators, including Clipper Travel, have been forced to initiate corporate layoffs, and local ferry systems have seen staff reductions due to the evaporated cross-border leisure demand.
| Destination / Sector | Primary Driver of Decline | Quantifiable Economic Impact |
| Las Vegas, NV | Loss of Canadian feeder market and aviation capacity. | 82,000 airline seats cut; visitor volume hits 2010 recessionary lows. |
| Miami / NYC | High exposure to short-term rental market contractions. | Severe vulnerability as national STR demand falls by 2.3%. |
| Orlando, FL | Strong U.S. dollar pricing out international family travel. | Double-digit percentage drops in municipal hotel tax revenues. |
| Coastal Resorts | Lack of high-spending, long-stay international leisure. | Resort Revenue Per Available Room (RevPAR) declines by 3.5%. |
| Northern Borders | Evaporation of cross-border vehicular and marine traffic. | Corporate layoffs at regional operators (e.g., Clipper Travel). |
The Aviation Paradox: Falling Traffic, Guarded Revenues
While on-the-ground hospitality bled out 9% of its revenue, the aviation sector experienced a slightly different trajectory. International passenger fare receipts for U.S.-flagged airlines declined by 3%, generating $2.8 billion in August 2026.
This paradox—a 3% drop in revenue against an 11.8% drop in actual human arrivals—highlights the aggressive yield management strategies of U.S. carriers. While the volume of travelers dropped sharply, airline yields (the price paid per ticket) remained stubbornly high. U.S. carriers likely executed strategic route rationalizations, cutting capacity in response to forecasted demand drops to artificially support high ticket prices. Furthermore, the aviation sector’s heavy reliance on premium business cabins may be masking the steeper drop in the economy leisure segment.
The Razor-Thin Trade Surplus: Americans Spend Abroad
Adding complexity to the U.S. economic picture is the robust strength of outbound travel. While foreign tourists are abandoning America, Americans are traveling internationally at record rates. In August 2026, U.S. travelers spent over $19.7 billion abroad, a 0.5% increase year-over-year.
When this $19.7 billion outbound outflow is subtracted from the $19.9 billion inbound influx, the United States was left with a shockingly narrow tourism trade surplus of just $157 million for the month. For the first eight months of the year (January through August 2026), total international visitor spending reached $165 billion—nearly 1% lower than the same period in 2025. While the U.S. maintains a cumulative surplus of nearly $5.6 billion year-to-date, the rapidly shrinking monthly margins highlight a precarious shift in the balance of trade.
Mitigating Sectors: Medical, Educational, and Labor Travel
The overall 5% plunge in visitor spending would have been a catastrophic freefall if not for the robust performance of non-discretionary, purpose-driven travel. Expenditure related to international education, medical tourism, and short-term worker logistics increased by more than 3%, reaching $6.4 billion. This sector alone accounted for 32% of total U.S. travel exports for the month.
- [ The Education Injection ] August is the prime month for international university intake. The tuition, housing, and living expenses of incoming global students provided a massive, non-negotiable cash injection that stabilized broader losses in the services export column.
- [ The Healthcare Premium ] The U.S. continues to dominate the global market for specialized healthcare. It draws affluent international patients whose itineraries are dictated by immediate medical necessity and access to cutting-edge treatments, rather than currency exchange rates or inflation.
- [ The Labor Logistics Backbone ] Agricultural, technical, and seasonal worker programs continue to drive consistent inbound metrics, sustaining specialized transit and temporary extended-stay lodging sectors that are insulated from leisure travel trends.
Shifting Tides: Source Markets Defying the Trend
While the overarching narrative is one of decline, destination marketing organizations are recalibrating their strategies to target source markets that are radically overperforming. The 11.8% overall drop in arrivals is heavily weighted by the collapse of traditional European and East Asian leisure travel. However, several emerging and neighboring markets are currently outpacing their pre-pandemic (2019) benchmarks.
According to recent aviation data, air arrivals from Mexico have surged to an impressive 148% of 2019 levels. India has also proven to be a powerhouse of resilient travel demand, with arrivals tracking at 126% of historical baselines. Meanwhile, Colombia continues to show robust growth, sitting at 124% of 2019 levels. For beleaguered cities like Miami and Las Vegas, pivoting marketing allocations to court these specific, high-growth demographics will be critical.
Forward Outlook: Corporate Travel as a Lifeline
As 2026 heads into its final quarter, the U.S. tourism industry is searching for domestic stabilizers. Across the U.S., total hotel room demand managed a microscopic 0.8% increase in August, entirely driven by domestic travel filling urban and airport hotels, which saw overall RevPAR grow by 2.0% (in stark contrast to the 3.5% drop in Resort RevPAR).
With inbound leisure travel suffering, the hospitality sector is clinging to domestic corporate travel as its primary lifeline for the winter. Forward-looking data offers a strong indicator of corporate resilience. As of mid-September, forward corporate hotel bookings were tracking 5.2% ahead of last year for October, 7.7% ahead for November, and an impressive 11.2% ahead for December. Furthermore, group room nights already booked for the fourth quarter are sitting 4.2% higher than at the same time last year.
U.S. tourism took a huge hit in August 2026 owing to reduced foreign visitors that resulted in a 9 percent fall in local consumption, which implies an economic crunch for locations ranging from Las Vegas to Miami.
The August 2026 NTTO figures provide a clear indication that the euphoria about travel after the pandemic has been corrected, and the world today is a fiercely competitive and price-sensitive one. In this scenario, the U.S. tourism industry has no choice but to move beyond its traditional appeal and focus on yield management and the corporate segment.
The post Las Vegas Joins Miami And Other US Hubs In 9% Tourism Revenue Drop As Sharp Decline In Overseas Arrivals Squeezes Local Economies appeared first on Travel and Tour World