
African Airlines Face a New Crisis as 137 Million Passengers Fuel Growth but Profits Collapse to Just 0.2%
-
Travel
-
-
7 mins
-
Travel and Tour World
-
Somudranil Sarkar
-


African airlines are expected to carry 137.3 million passengers in 2026, but 0.2% profit margins, blocked funds and high costs threaten growth.
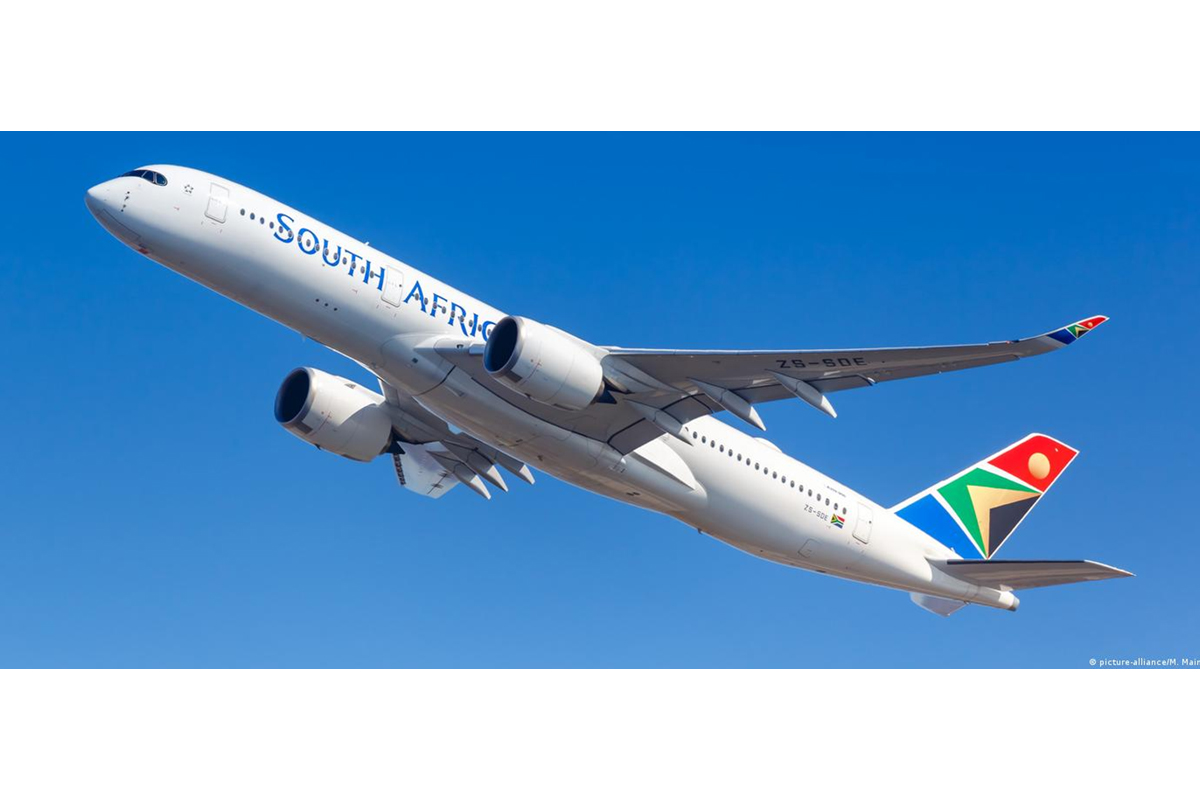
Africa’s aviation sector is approaching a defining moment in 2026 as passenger demand accelerates while airline profitability remains among the weakest in the world. African airlines are expected to transport 137.3 million passengers in 2026, representing a 21.5 per cent increase from the previous year, yet industry profit margins are forecast at just 0.2 per cent.
The contradiction is becoming one of the most important issues facing the continent’s aviation industry. Passenger demand is expanding rapidly, but airlines are struggling to convert that growth into sustainable financial returns.
The challenge was highlighted at the African media roundtable held at Nairobi’s Sarit Expo Centre under the theme Resilient African Aviation: Partnerships, Empowerment, Profitability. Industry discussions focused on the structural costs and operational barriers preventing African carriers from fully benefiting from the continent’s growing aviation market.
African Airlines Face a Massive Demand Opportunity
Africa’s demographic and economic trajectory provides a powerful foundation for future air travel.
The continent’s population is projected to reach 1.58 billion by 2026, while its median age is expected to remain just 19. Average annual economic growth has been placed at 4.3 per cent.
These characteristics create significant long-term potential for aviation.
A young population can generate rising demand for mobility, education, business travel, tourism and employment-related journeys. Economic expansion can also increase the number of consumers and businesses capable of using air transport.
Yet aviation penetration remains remarkably low.
Only around seven per cent of the African population is currently associated with air travel penetration, leaving a substantial portion of the potential market undeveloped.
Passenger Growth Is Not Translating Into Profit
The expected 137.3 million passengers represent a major opportunity for African airlines.
However, the projected 0.2 per cent profit margin reveals how little of the additional demand is currently translating into financial strength.
A rapidly growing passenger market would normally be expected to create economies of scale and stronger commercial performance. In Africa, however, carriers are being confronted by exceptionally high operating costs and structural constraints.
The result is an aviation market where demand is expanding faster than profitability.
This creates a significant strategic problem because airlines require sustainable profits to invest in aircraft, technology, staff, safety, connectivity and network expansion.
Without adequate returns, passenger growth alone cannot guarantee long-term aviation development.
Taxes and Charges Consume Up to 40% of Ticket Prices
One of the most significant barriers identified for African carriers is the burden of taxes, fees and charges.
These costs account for approximately 35 per cent to 40 per cent of ticket prices, compared with a global average of around 20 per cent.
The difference places African airlines at a substantial competitive disadvantage.
Higher taxes and charges can increase fares for passengers while simultaneously reducing the flexibility available to airlines when setting competitive prices.
The impact can become particularly significant in price-sensitive markets, where higher ticket prices can discourage additional demand.
The resulting cycle can limit both affordability for travellers and profitability for carriers.
$774 Million in Airline Funds Remain Blocked
Financial liquidity is being further affected by blocked airline funds.
Governments across Africa were withholding approximately $774 million in blocked airline funds as of March 2026, representing the largest regional share of trapped airline funds worldwide.
The issue is part of a broader $1 billion blocked-funds crisis affecting Africa and the Middle East.
Foreign-exchange shortages and administrative barriers have contributed to the problem, preventing airlines from repatriating money earned through ticket sales and other commercial activities.
For airlines operating on extremely narrow margins, delayed access to revenue can create serious cash-flow pressure.
Ethiopian Airlines Has $90 Million Trapped Overseas
The scale of the problem is illustrated by Ethiopian Airlines, Africa’s largest carrier.
Approximately $90 million belonging to the airline is reported to be trapped in overseas markets.
For a major airline, the inability to freely access funds generated through international operations can affect liquidity and financial planning.
For smaller African carriers, similar restrictions could potentially create even greater difficulties because their financial reserves and access to alternative capital may be more limited.
The blocked-funds problem therefore represents more than an accounting issue. It directly affects the ability of airlines to use their own revenues to support ongoing operations.
Aircraft Deliveries Remain Heavily Uneven
Africa’s aviation infrastructure challenge is also reflected in the distribution of new aircraft deliveries.
The continent receives only approximately two per cent of global aircraft deliveries.
By comparison, Asia-Pacific accounts for 35.6 per cent and Europe for 24 per cent.
The disparity limits the speed at which African airlines can modernise their fleets and expand capacity.
New aircraft can improve fuel efficiency, passenger experience and operational performance, while additional capacity can allow airlines to develop new routes and increase connectivity.
Limited access to new aircraft therefore represents another constraint on the industry’s ability to respond to rising demand.
Africa Needs Up to $30 Billion in Aviation Infrastructure
The continent’s infrastructure requirements extend beyond aircraft.
Africa is estimated to require between $25 billion and $30 billion in airport and air navigation infrastructure investment over the next decade to accommodate rising passenger volumes.
The requirement covers the infrastructure needed to support the expected growth in aviation activity.
As passenger numbers increase, airports and air navigation systems must be capable of handling greater traffic safely and efficiently.
Insufficient infrastructure can create congestion, operational inefficiencies and additional costs for airlines.
Investment in airports and air navigation infrastructure is therefore being identified as a critical component of transforming passenger growth into sustainable aviation development.
Sahel Conflicts Are Increasing Airline Operating Costs
Geopolitical instability is adding another layer of pressure.
Conflict-related airspace closures across the Sahel region are increasing operational costs for airlines.
A no-fly corridor extending approximately 4,000 kilometres across Niger, Mali, Sudan and Libya is forcing carriers to take longer routes.
Longer flight paths require additional fuel and can increase crew, aircraft utilisation and other operational expenses.
For airlines already operating with margins of only 0.2 per cent, additional fuel consumption can have a disproportionate effect on profitability.
The issue also demonstrates how geopolitical conditions can directly influence commercial aviation even when passenger demand remains strong.
Fuel Costs Continue to Pressure Airline Economics
Fuel remains one of the most significant expenses for airlines globally, and African carriers face additional challenges because of high and unhedged fuel costs.
The impact of fuel-price exposure is not limited to Africa.
Global carriers such as Ryanair have also been affected by fuel-cost pressures, leading to reductions in traffic targets and warnings about declining profits.
For African airlines, however, the consequences can be particularly severe because fuel expenses are being combined with high taxes, blocked funds, infrastructure limitations and airspace restrictions.
The combined pressure can significantly reduce the financial benefit created by additional passengers.
AFRAA Calls for Coordinated Action
The African Airlines Association, or AFRAA, represents 50 member airlines responsible for more than 85 per cent of Africa’s international air traffic.
The association has called for coordinated action involving governments, regional organisations and financial institutions.
The objective is to ensure that passenger growth can be converted into sustainable profitability rather than being absorbed by structural costs.
AFRAA has identified the release of blocked airline funds, reduction of aviation taxes and charges, and implementation of existing liberalisation policies as important steps.
Such measures could help improve airline liquidity while making air travel more competitive.
Abderahmane Berthe Warns of a Capacity Gap
AFRAA Secretary General Abderahmane Berthe has highlighted the difference between Africa’s aviation potential and its current operating capacity.
The central concern is that airlines are being expected to support economic integration and trade growth while operating under extremely narrow margins.
The combination of blocked funds, high costs and external shocks is limiting the ability of carriers to respond effectively to demand.
The warning carries wider economic significance because aviation provides connectivity for tourism, trade, investment and business activity.
If airline networks remain financially constrained, the impact could extend beyond carriers to the wider African economy.
Afreximbank and Development Institutions Have a Critical Role
Financial institutions are expected to play a major role in resolving Africa’s aviation infrastructure and financing challenges.
Afreximbank, the African Development Bank and the African Union Commission have been identified as important partners in financing and infrastructure development.
Their involvement can help address some of the capital requirements associated with airport infrastructure, air navigation systems and broader aviation development.
The participation of regional financial institutions is particularly important because aviation infrastructure projects often require significant long-term investment that cannot be supported entirely through airline balance sheets or individual government budgets.
Liberalisation Could Unlock More Regional Connectivity
The implementation of existing aviation liberalisation policies is another area identified as requiring urgent attention.
Greater market liberalisation could support improved connectivity between African countries and create opportunities for airlines to develop more efficient regional networks.
Africa’s large geography and growing population make efficient intra-continental connectivity particularly important.
Improved air links can facilitate tourism, trade, investment and movement between economic centres.
However, liberalisation must be accompanied by financial sustainability. Greater market access alone cannot solve the profitability problems facing carriers if taxes, fuel expenses, blocked funds and infrastructure costs remain elevated.
Aviation Could Become a Major Economic Growth Engine
The opportunity created by Africa’s expanding passenger market extends far beyond airline revenues.
Aviation can support tourism development, facilitate international trade, connect businesses and create employment.
For a continent with a young population and projected economic growth of 4.3 per cent annually, reliable air connectivity could become an increasingly important component of economic integration.
The current challenge is therefore to ensure that aviation capacity develops at a pace consistent with demand.
Without adequate investment and regulatory reform, passenger growth could increasingly expose rather than solve structural weaknesses within the industry.
Africa’s Aviation Paradox Reaches a Critical Point
African airlines are expected to carry 137.3 million passengers in 2026, representing a 21.5 per cent increase from the previous year.
Yet profitability is projected at only 0.2 per cent.
The extraordinary gap between demand and financial performance highlights the structural challenges facing African aviation.
Taxes and fees consuming up to 40 per cent of ticket prices, approximately $774 million in blocked airline funds, limited aircraft deliveries, high fuel costs and conflict-related airspace restrictions are collectively undermining the industry’s ability to benefit from passenger growth.
At the same time, Africa requires between $25 billion and $30 billion in airport and air navigation infrastructure investment over the next decade.
The opportunity remains substantial. A population projected at 1.58 billion, a median age of 19 and annual economic growth of 4.3 per cent provide powerful long-term foundations for aviation expansion.
However, passenger numbers alone cannot create a sustainable aviation industry.
For African aviation to convert its growing demand into meaningful profitability, governments, airlines, financial institutions and regional organisations will need to address the structural costs simultaneously. Releasing blocked funds, reducing excessive taxes and charges, expanding infrastructure, improving aircraft access and implementing liberalisation measures could determine whether the continent’s aviation boom becomes an economic growth engine or remains trapped behind exceptionally thin margins.
The post African Airlines Face a New Crisis as 137 Million Passengers Fuel Growth but Profits Collapse to Just 0.2% appeared first on Travel and Tour World